2008 Didn't Punish Real Estate. It Punished Structure.
2008 Didn't Punish Real Estate. It Punished Structure.
You own real estate at low leverage. Fixed-rate debt. A market with real jobs and real demand. And some part of you still tenses when someone brings up 2008.
That tension is expensive.
Not because 2008 wasn't real. It was the worst financial event since the Great Depression. The fear is expensive because it attached itself to the wrong target. You are bracing against a danger that mostly didn't touch people who own the way you own. Meanwhile, the danger that actually did the damage is the one most people still can't name.
The lesson of 2008 got mislabeled. And a mislabeled lesson is worse than no lesson — it makes you cautious about the wrong thing and confident about the wrong thing at the same time.
Here is the single idea this article is built on:
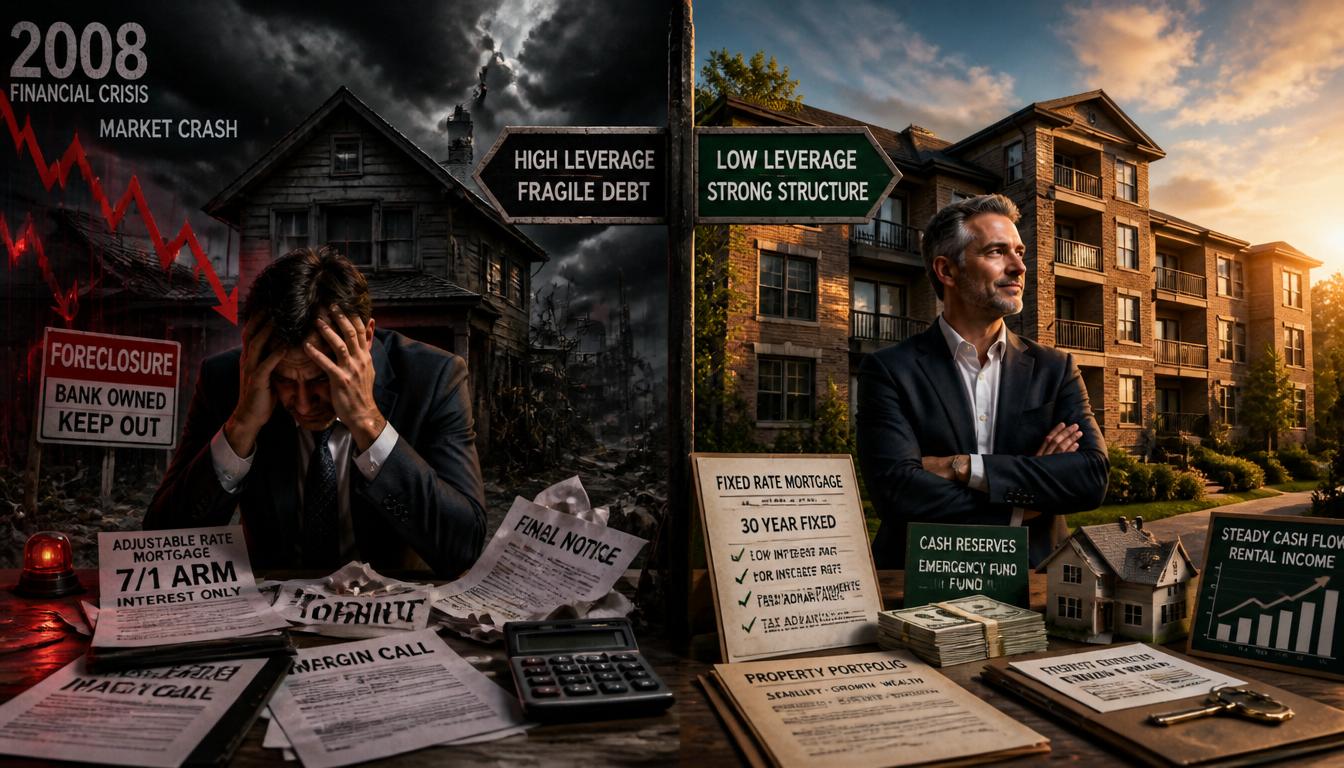
2008 did not punish real estate. It punished structure.
The crash did not care whether you owned property. It cared how you owned it — how much you borrowed, what kind of debt you carried, how much cushion stood between you and zero, and whether you could avoid selling at the bottom.
Same asset. Opposite outcomes. The difference was almost entirely structural.
Once you see that, the thing you should fear stops being "real estate" and becomes something far more specific — and far more controllable.
What Actually Happened
Start with what the crisis was, mechanically, underneath the headlines.
For years, an assumption hardened into a fact in nearly every corner of the mortgage market: home prices would keep rising. The Financial Crisis Inquiry Commission — the federal body that ran the official postmortem — later concluded the collapse was avoidable, the product of excessive borrowing and risk-taking by both households and Wall Street, and of trillions of dollars wagered on the belief that home prices would always go up and borrowers would rarely default.
That assumption did something subtle. It made underwriting feel optional. If the house is always worth more next year, the borrower's income barely matters — the rising collateral covers the risk.
So standards loosened across the system. The part of the story usually told as "anyone with a pulse could get a mortgage" is real, but the cause is not the cartoon version. It wasn't one politician or one bill. It was an incentive structure. Lending had shifted to an originate-to-distribute model: the broker who wrote the loan sold it within weeks, bundled it into a security, and passed the default risk to someone else. As the Federal Reserve later put it plainly, when the originator no longer bears the cost of default, the originator has little reason to check whether the borrower can actually pay.
Layer adjustable rates, teaser rates, and interest-only structures on top of that, and you get a system that worked beautifully in exactly one condition: prices going up.
Then prices stopped going up.
The S&P CoreLogic Case-Shiller national index peaked in 2006 and fell roughly 27% to its 2012 trough — the deepest national home-price decline since the Depression. In the hardest-hit metros, the drop was closer to 50%. By the end of 2009, more than one in four mortgaged homes in America was underwater — the loan balance was larger than the house was worth.
That is the moment the structure decided who survived.
Who Actually Got Hurt
When prices fell, the refinancing escape hatch slammed shut. You cannot refinance a house you no longer have equity in. The St. Louis Fed's research on the period is blunt about this: falling prices were a bigger shock to vulnerable borrowers than unemployment or rising rates, because once the equity was gone, the exits were gone.
Now watch where the damage concentrated.
Subprime and Alt-A loans were a minority of all mortgages — but they drove the majority of the foreclosure surge. The borrowers who got crushed shared a profile: little or no equity, adjustable or teaser-rate debt that reset to payments they couldn't carry, and no cushion to wait out the storm. By 2008, roughly one in four subprime adjustable-rate mortgages was seriously delinquent or already in foreclosure.
The sequence was mechanical. No equity, plus a payment that jumped, plus a house worth less than the loan, plus no ability to refinance — and the only remaining exit was to sell or surrender at the worst possible moment. They became forced sellers. The forced seller doesn't get to wait for the recovery. The forced seller is the loss.
Now picture the other owner. Low loan-to-value, so a 20% or even 30% price drop still left equity in the building. A fixed 30-year rate, so the payment never moved no matter what the Fed did. A property in a market with real employment, so the tenant kept paying and the cash flow held.
That owner watched the same price decline on paper. But nothing forced their hand. The payment was stable. The equity cushion absorbed the drop. The cash flow covered the carry. They were never made to sell. So the paper loss stayed on paper — and reversed when the market did.
Same asset class. Same crash. One was destroyed; the other was inconvenienced. The variable was never "real estate." It was structure.
The Real Lesson Is Not "Avoid Real Estate"
The lesson disciplined owners took from 2008 was often the wrong one: property is dangerous. The accurate lesson is narrower and more useful: fragile structure is dangerous.
Four structural truths fall out of the wreckage:
Fixed beats floating in a stress event. A fixed 30-year payment is a contract that doesn't reprice when the world panics. Floating-rate and teaser debt hands the lender a lever to pull at the exact moment you can least afford it.
Equity cushion is what converts a price drop from catastrophe into a footnote. Low LTV is not timidity. It is the buffer that keeps a paper loss from becoming a forced sale.
Cash flow and liquidity are survival, not yield. The owner who can cover the carry and reach cash without selling never becomes a forced seller.
The one who can wait, wins. Almost every 2008 wipeout was a forced action at the bottom. Almost every 2008 survival was the freedom to do nothing.
Notice that three of the four come down to the same thing: not being forced to act. We covered the broader mechanics of that elsewhere — the ability to access capital without being made to sell the asset that produced it — in Liquidity Without Liquidation. 2008 is the stress test that proves the point. The thing that destroyed people was not the price drop. It was needing money, or needing out, at the precise moment the market was least willing to give them either.
Where the Buffer Lives
Which raises the question the disciplined owner should actually be asking. Not "is real estate safe?" but "where is my buffer, and will it be there when prices are falling and credit is tightening at the same time?"
That is harder than it sounds, because in a 2008-style event, most buffers fail together. Home equity evaporates exactly when you'd want to borrow against it. Bank lines get pulled. A stock portfolio you'd planned to lean on is down with everything else. The assets you owned for protection turned out to depend on the same conditions as the asset you were protecting. We took that idea apart in Every Asset You Own Depends on Something: owning more things inside the same system isn't a buffer — it's the same risk wearing more outfits.
A real buffer has to do two things a stressed market won't: hold its value when other assets fall, and stay reachable without forcing a sale.
The obvious answer is cash. And cash genuinely works here — it is the cleanest non-correlated buffer there is. But hold a 2008-sized cushion in cash for a decade and you pay for it the whole time: it sits idle, earns little, and loses ground to inflation while it waits for a crisis that may be years away. So the more precise question a sophisticated owner asks isn't "cash or no cash?" It's whether that buffer can do a second job while it waits.
That is the narrow place where properly structured whole life cash value earns a look — not as an investment, and not as a pitch, but as a mechanism with a few specific properties:
It can do two jobs at once. With a properly structured policy, you can borrow against the cash value while the full balance keeps compounding underneath the loan — the same dollar serving as a reserve and continuing to grow. Cash in a checking account can only do one job at a time. This is the feature that separates it from a savings account, and it is the entire point.
Its growth is contractually defined, not market-linked. It does not fall because real estate fell or because equities fell. In a year when your home equity and your portfolio are both down, that is precisely the kind of non-correlated value a buffer is supposed to have.
Accessed correctly, a policy loan is not a taxable event. You are borrowing against the asset, not selling it — which matters more the higher your income and the worse the timing.
The same pool transfers income-tax-free at death. One reserve that buffers you in life and passes cleanly, typically outside probate, to the next generation.
None of this is magic, and all of it depends on the structure being built and used correctly — "properly structured," "accessed correctly," "contractually defined," subject to the insurer's guarantees. The point is simply this: the 2008 survivors won because they were never forced to sell. The question worth sitting with is where your never-forced-to-sell money lives — and whether it's working while it waits.
2008 was not a verdict on real estate. It was a verdict on fragility.
The disciplined owner — low leverage, fixed debt, real market, real cash flow — who still flinches at the memory is flinching at a fire that burned down a different kind of house. The fire was real. The house was built differently.
Fear the structure that forces your hand. Not the asset that, structured well, never did.
The Critical Thinking Three
1. If your local market dropped 30% next year and held there for five years, what in your structure would force you to act — and what would let you do nothing? The honest answer tells you whether you own like a 2008 survivor or a 2008 casualty. They looked identical right up until they were forced to choose.
2. Every buffer you're counting on for the next downturn — your home equity, your credit lines, your portfolio — ask of each one: does this hold its value and stay reachable specifically when everything else is falling? Or does it quietly depend on the same conditions as the thing it's supposed to protect? A buffer that fails in the same weather as the asset isn't a buffer.
3. The 2008 survivors won by being able to wait. So where, exactly, is the money that lets you wait — and is it earning its keep while it sits, or are you paying to hold it idle against a crisis that hasn't arrived? Most people have never located that money on purpose. They find out where it was, or wasn't, during the event itself.
If this reframed what you thought 2008 was actually about, two next steps:
Subscribe to Wealth & Liberty for more pieces that question the defaults most financial advice never examines.
And if you want to pressure-test how your own structure would hold up in a forced-seller event — leverage, debt type, and where your never-forced-to-sell money actually lives — the team at Producers Wealth works exclusively with business owners and high-income earners on exactly that question.
Wealth & Liberty is an educational platform. Nothing in this article constitutes financial, legal, or tax advice. Always consult a qualified professional before making financial decisions.