Choose Your Hard: Every Path Costs You — the Question Is What Yours Builds
Choose Your Hard
Building a business is hard.
So is sitting across a desk from another grown man and asking his permission to take Saturday off — to go watch your son play baseball.
Both are hard. Only one of them ends with you owning your own time.
Most financial advice sells the opposite story: that somewhere out there is an easy path, and the job of money is to find it. Save enough, index enough, wait long enough, and one day the hard part ends.
It doesn't end. It relocates.
The Cost Is Fixed. The Return Is Not.
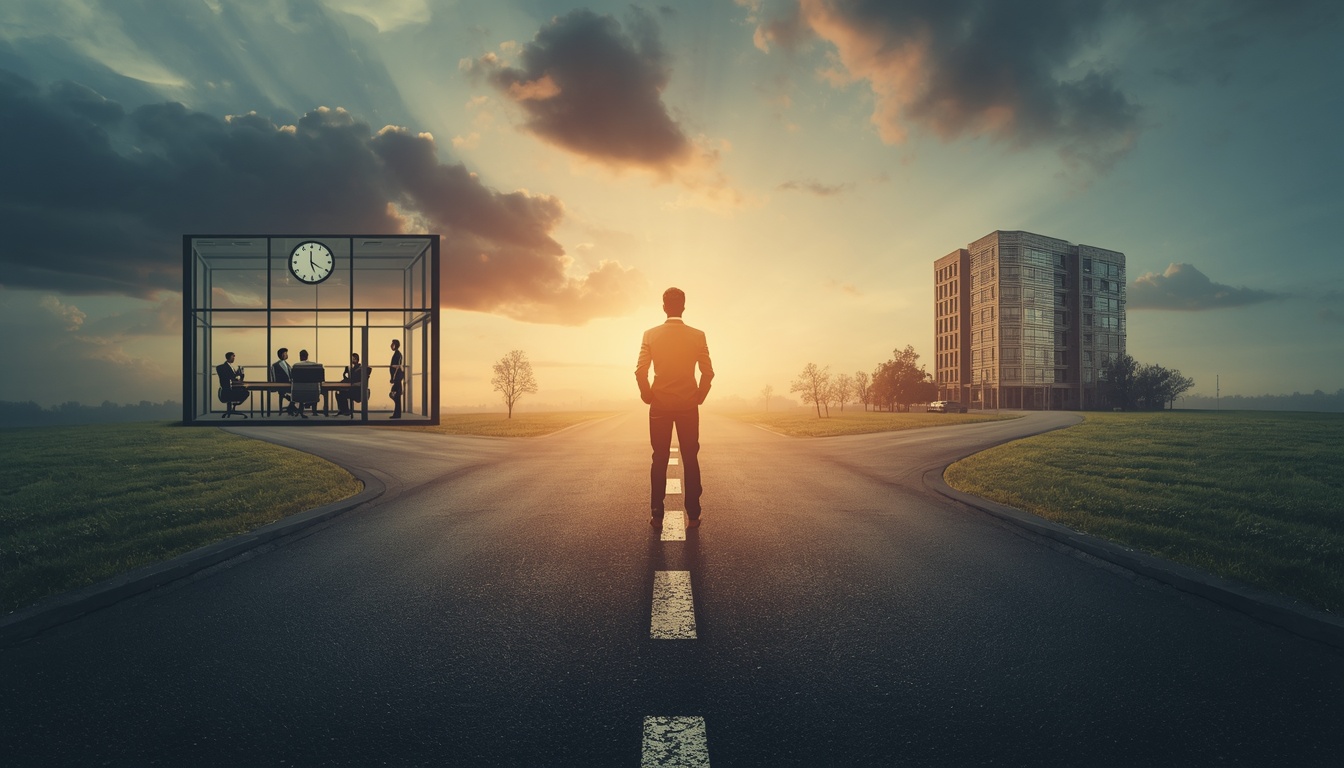
Here is the idea this whole piece rests on: you do not get to choose between hard and easy. That choice was never on the table. You only get to choose which hard you are going to pay for — and the two hards do not build the same thing.
One hard buys you predictability and charges you a ceiling. The other charges you volatility and leaves the ceiling off.
Every path extracts something from you. The only question worth asking is whether what it extracts compounds into something you own — or evaporates onto someone else's balance sheet.
Two Kinds of Hard
Start with the honest case for the safe path, because conventional advice gets something right.
A steady job is real security. Predictable income, a known schedule, someone else absorbing the risk when the quarter goes bad. For most of human history that stability was the dream, and waving it away is its own kind of foolishness.
But predictability has a price, and the price is structural.
Your upside is capped by a salary band you didn't set and can't see. And your time — the actual hours of your one life — gets rented back to you in permission slips. You can be the best in the building and still need a yes from someone who wasn't at the game.
The ownership path inverts every term of that deal. No floor. No guaranteed income. Brutal cycles, lumpy cash flow, nights you lie awake doing math.
But the ceiling is gone — and, the part that matters most, what you build can become an asset you own and hand to someone else.
The Part Nobody Tells You
Here the data gets honest, and it is far more useful than the motivational version.
Owning a business is not automatically the higher-upside path. Gallup's research is blunt about it. Business owners who employ others report a median household income around $175,000 and roughly $550,000 in assets outside the business. Employees report about $110,000 in household income and $130,000 in assets. That gap is real.
But the solo operator — the self-employed person with no employees — shows the lowest median assets of any group Gallup measured, around $46,000. Owning a business without employees showed no meaningful income or wealth advantage over simply holding a job.
Read that twice. The upside is not in "being your own boss." Plenty of people are their own boss and broke.
The upside lives on the other side of one specific line: building something that produces value beyond your own two hands. Only about one in eleven business owners ever crosses it. That crossing — not the quitting, not the logo, not the title — is where the leverage actually lives.
So the line to carry isn't "jobs are a trap." It's quieter and truer:
The goal is not to avoid hard work. The goal is to choose hard work with leverage.
Income Is the Visible Difference. Control Is the Invisible One.
The salary-versus-business gap is easy to see. The deeper difference is harder to notice and matters more.
A salary is income you are permitted to earn. A business is income you own the rights to. Same dollars on the surface; entirely different jurisdictions of control underneath. Every dollar you earn or hold sits somewhere on that spectrum, whether you've ever mapped it or not.
And the same question — permission or ownership — returns later, in how you hold what you've built. Most people spend a lifetime accumulating wealth they're only allowed to touch on someone else's terms, mistaking the cage for independence. The choice between two kinds of hard is that same choice, showing up earlier.
The Trap on the Other Side
The ownership path has a failure mode the cheerleaders skip.
The owner's income is lumpy and the cycles are merciless. And the moment your business most needs capital is usually the exact moment the bank, the market, or the economy decides to say no.
An owner without a private pool of capital hasn't escaped permission. He has only swapped the boss for the lender.
So the thing the employee rarely thinks about becomes survival-critical for the owner: a base of capital that is liquid, that you control, that doesn't fall when your business cycle falls, and that doesn't require anyone's approval to reach. Strategy first — then the vehicle.
"Why not just hold cash?" is the fair objection, so answer it directly. Cash sitting idle as a buffer earns nothing and quietly loses ground to inflation. And the moment you deploy it into the business, it stops being a buffer — you can't spend the same dollar twice.
A properly structured participating whole life policy is built around that exact tension. The cash value keeps compounding on the full balance even while you borrow against it to fund the business — the same dollar doing two jobs at once. Its growth is contractually defined rather than market-linked, so it doesn't drop when the market or your sector drops. Access comes through policy loans that, structured and used correctly, aren't a taxable event — a distinction that matters more with every step your income climbs.
And the same pool that buffers your business while you're alive transfers income-tax-free, typically outside probate, to the next generation when you're gone. One asset doing defensive work on both sides of a lifetime — subject, as always, to proper structure and the insurer's guarantees.
That last part is the quiet point. The asset that lets you stop asking permission in your own lifetime is the same one that hands your children a head start you never got — without the tax code taking its cut on the way through.
So Choose
Both roads are hard. Anyone who tells you otherwise is selling the fantasy.
Pick the hard that builds something with your name on the deed. Then build the capital structure that keeps it yours — and keeps it theirs, after you.
The Critical Thinking Three
If your income stopped tomorrow, whose permission would you need to restart it — and how many people in your life can switch off your livelihood with a single decision?
Strip out the paycheck. What have you actually built in the last five years that you own — something that keeps producing, or transfers to your children, whether or not you show up Monday morning?
You are going to work hard either way; that part is already decided. So answer the only question still yours to answer: when the hardest decade of your effort is behind you, will you own the thing it built — or will you have spent it making someone else's asset more valuable, one requested Saturday at a time?
If you want to see what a capital structure built for an owner actually looks like — liquid, controllable, and outside anyone's permission — the team at Producers Wealth builds exactly that for business owners and high-income earners. Start the conversation →
Not ready to talk yet? Join the Wealth & Liberty newsletter — one idea a week on building wealth that doesn't need anyone else's approval.
This article is educational and general in nature. It is not financial, tax, or legal advice. Whole life insurance guarantees are subject to the claims-paying ability of the issuing insurer; policy loans accrue interest and reduce cash value and death benefit if not repaid. Consult a qualified professional about your specific situation.