Whenever you find yourself on the side of the majority, it is time To Reform. - Mark Twain
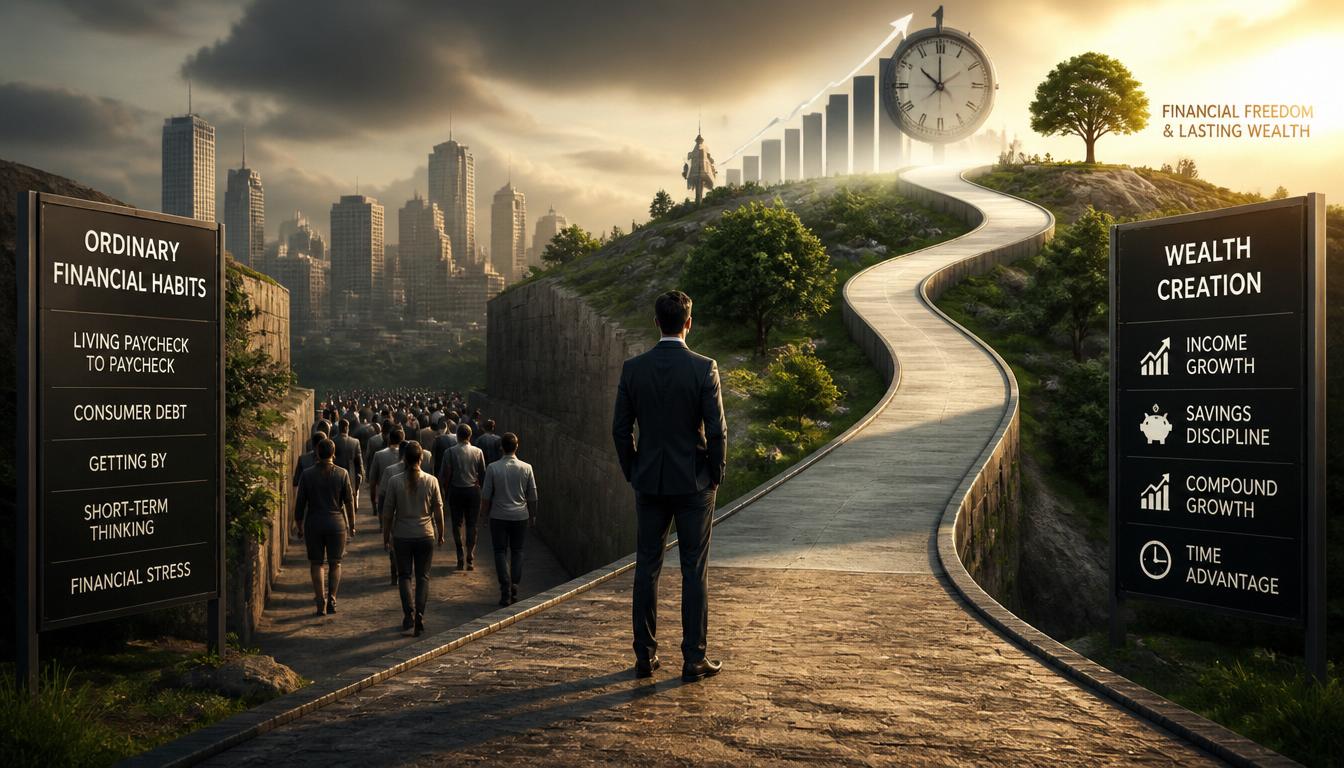
Purusing Average; shoot for the stars
A Plan to Be Average
You get one life. One shot at building something — for yourself, for the people who depend on you, for whatever you want to leave behind. So it's worth asking a blunt question about the financial advice almost everyone follows: what is it actually aiming at?
Max out the 401(k). Buy index funds. Diversify. Dollar cost Average. Roth IRA. HSA. Stay the course. It sounds responsible. But look closely at what that plan is built on and what it's designed to produce, and you find something uncomfortable. It is, almost by definition, a plan to be average. It's built on average returns. It aims at an average outcome ). And — as we're about to see — even when it works flawlessly, average is roughly what it delivers.
Let's prove it. Not with a strawman, but with the strongest possible version of the conventional case.
Give Conventional Advice Every Advantage
Meet our investor. She's 25, earning the median income for a full-time worker her age — about $60,000 a year, per the Bureau of Labor Statistics. She does everything the industry recommends, flawlessly, for forty years:
She saves 15% of her income, every year, without fail.
She gets a steady 3% raise each year, and her contributions rise with it.
She never loses her job. Never faces a divorce, a disability, or a medical event that interrupts her saving.
She invests entirely in a low-cost S&P 500 index fund.
She never panic-sells, never chases a hot stock, never tries to time the market. She is the disciplined investor the behavior studies say almost no one actually is.
We'll even be generous on the return. We won't use the market's often-quoted 10% average — because that arithmetic average overstates what real portfolios actually compound at once losses and allocation shifts are accounted for. Instead we'll use 7% as her net portfolio growth rate: a figure that already bakes in market losses, the gradual shift toward bonds as she ages, rebalancing, and ordinary fund costs.
Seven percent, compounding for forty years, on a disciplined and rising contribution. This is about as good as the conventional path gets.
What Forty Perfect Years Produce
Run the math on those assumptions and our investor retires at 65 with approximately $2.6 million.
That's a real number, and it's not nothing. On its face, the system worked — do the responsible thing for four decades and become a multimillionaire.
But a retirement balance is a nominal figure, and you don't spend nominal dollars. You spend purchasing power. So the honest question isn't "how big is the number?" It's "what will that number buy?"
At 3% inflation over those same forty years, $2.6 million in 2065 dollars carries the purchasing power of about $808,000 today.
Apply the standard 4% withdrawal rule and her first year of retirement income is roughly $105,000 — which, again in today's purchasing power, is about $2,700 a month. She holds most of it in a traditional, tax-deferred account, so after ordinary income tax on withdrawals she's living on something closer to $2,150 a month in today's dollars.
That is the best-case outcome. Forty years. Zero mistakes. Zero setbacks. A disciplined saver in one of the most favorable market windows in history — and the result is a comfortable-but-modest retirement that a single serious illness or a few bad years of sequence-of-returns risk could still unravel.
This isn't an argument that the market failed. She made money. The market did its job. The point is narrower and more useful: even when everything goes right, the conventional plan produces a modest, average result — and almost nothing ever goes entirely right.
📖 Related: The Misrepresentation of the "Average Rate of Return" — The companion to this piece. It runs the same kind of investor through real year-by-year losses, fees, and taxes, and shows why the projections people are shown at 35 look nothing like the balances they find at 65.
So if the best case is only average, the real question is: what actually moves the number?
The Only Four Variables That Build Wealth
Here is what almost no one has laid out for them plainly. There are only four inputs that determine how much wealth you accumulate. Every strategy, every product, every piece of advice ultimately works by changing one or more of them:
Wealth = Income × Savings Rate × Compound Growth × Time
That's it. There is no secret fifth variable. Picking stocks, timing the market, finding the next hot fund — those aren't independent levers. At best they're attempts to nudge one variable, compound growth, usually by taking on more risk.
Look at what each variable does to our investor's $2.6 million best case, changing one thing at a time.
Earn more. Double her income and keep the same 15% savings rate, and the ending balance doubles — to about $5.3 million. More income means more dollars working, as long as lifestyle doesn't rise to swallow the raise.
Save more. Leave her income at $60,000 but raise her savings rate from 15% to 40%, and she retires with roughly $7 million — nearly triple the baseline. Same income. Same market. She simply kept more of what she earned.
Earn a higher return. Push her net growth from 7% to 9% and she reaches about $4.2 million. Meaningful — but here's the catch. Reliably earning two extra points, every year, for forty years, is something almost no investor and few professionals actually achieve. And when it does happen, it usually comes from taking on more risk, which reintroduces exactly the losses that drag real compounding below the average in the first place.
Give it more time. Start at 20 instead of 25 and the same plan grows to about $3.9 million. Five years, worth more than a million dollars — because compounding is exponential at the end. Time is the most powerful variable, and the only one you can never buy back.
Now hold those side by side. To match the 40%-saver's $7 million using return alone, our baseline investor would need to earn about 11% a year, every year, for forty years — a return that would put her in rarefied company and demand enormous risk to chase. Or she could simply decide, on payday, to save more.
The Variable Wall Street Sells You
Here's the uncomfortable part. Of the four variables, conventional financial advice is almost entirely focused on one: compound return.
"Put your money in the market." "Stay diversified." "Don't miss the ten best days." Nearly the entire conversation is about squeezing another point or two out of a portfolio — the variable you control the least and that carries the most risk to move.
The variables you actually control — how much you earn and how much of it you keep — barely get mentioned. That's not an accident. There's no product to sell you on your own savings rate. There's no management fee attached to your decision to grow your income. The industry earns its living on the one variable it can package, so that's the one variable it talks about.
For a business owner or high earner, this is worth sitting with. Your biggest wealth lever is almost never another percentage point of portfolio return. It's your income, your savings rate, and how efficiently each dollar you keep is put to work.
Why Aim for Average?
Which brings us back to the blunt question at the start. You get one life. Why would you point it at average on purpose?
The usual answer is that ambition is reckless and "average" is safe. But look at what the conventional plan actually does: it bets your entire outcome on the one variable you don't control — market return — and quietly ignores the three you do. That's not caution. That's aiming low and calling it prudence.
Real ambition, applied to money, isn't gambling on the next hot fund. It's the opposite. It's refusing to leave your one life to the variable you can't govern, and instead pulling hard on the three you can: earn more, keep more, structure smarter, and start now. "Shoot for the stars" isn't a motivational poster here — it's the rational response to having one life and four levers, three of them in your own hands.
And the goal was never a comfortable-enough retirement anyway. The reason to build wealth is control, protection, and something worth passing on. Average doesn't buy those. A worthy goal does — and reaching it starts with optimizing the variables that are actually yours.
Where a Fourth Idea Comes In
Once you see wealth as those four variables, a different question opens up — one the "just buy index funds" framing never reaches. It's not only which variable you optimize. It's whether a single dollar can improve more than one variable at a time.
This is where sophisticated capital allocators — family offices, banks, endowments — think differently than the retail saver. And it's the reason a properly structured whole life policy shows up on the balance sheets of institutions that could invest in anything.
📖 Related: Why Banks Love Life Insurance — Bank of America holds over $25 billion in life insurance on its balance sheet. They are not doing it for the yield. They are doing it because uninterrupted, guaranteed, tax-advantaged growth has a value that average-return comparisons consistently understate.
Start with the obvious objection: if the goal is just to protect some dollars, why not hold cash? Because cash doesn't compound, and inflation quietly taxes it every year — the same purchasing-power erosion that turned our investor's $2.6 million into $808,000. Cash protects the number and destroys the value.
Properly structured whole life answers the four-variable problem on axes the market can't touch.
It protects the Time and Compound Growth variables from interruption. Its growth is contractually defined and non-correlated — it doesn't fall when markets fall. No drawdowns, no volatility drag, no years spent digging out of a hole just to break even. The compounding sequence is never reset. Over a long horizon, uninterrupted growth at a lower rate frequently beats higher average growth that keeps getting interrupted.
It also improves capital efficiency — the quiet lever behind the whole idea. In a properly structured policy, the full cash value keeps compounding even while you borrow against it. The same dollar does two jobs: it stays invested and compounding, and it's available as capital to fund the opportunity, the business need, or the emergency. Access comes through policy loans that, done correctly, aren't a taxable event — a distinction that matters more the higher your income and bracket. You're no longer forced to choose between "keep it saved" and "put it to use." The dollar does both.
And at the end, the same pool that buffered you in life transfers to your family income-tax-free, typically outside probate. One asset, doing defensive work on both sides of a lifetime.
None of this is a promise of a higher return than the stock market — and that's the point. It isn't competing on variable #3, where the marketing lives. It improves the equation on the variables the market leaves exposed: protecting your time and your compounding, and letting the same dollar work twice. (All of it assumes a properly structured policy, accessed correctly, subject to the insurer's contractual guarantees — the specifics matter enormously, which is exactly why they're worth understanding before, not after.)
📖 Related: Compared to What? The Financial Spectrum No One Explains — Before you evaluate any return, you have to ask what job that dollar is assigned to do. A comparison only makes sense when both sides of it are doing the same job.
What This Means for Your Plan
None of this is an argument to abandon the market. You can build real wealth in public markets, and low-cost index funds have virtues worth keeping.
The argument is narrower. If you optimize only the one variable the industry sells — return — you're leaning on the lever with the least control and the most risk, and ignoring the three levers that are actually yours. The best-case scenario shows that even flawless execution of the conventional plan produces an average result. The four-variable view shows why, and where the real leverage has been hiding the whole time.
You don't become wealthy by being the best guesser about next year's market. You become wealthy by earning more, keeping more, protecting your compounding from interruption, giving it time — and structuring your dollars so each one does as many jobs as possible.
You get one life. Aim it at something better than average.
The Critical Thinking Three
If you followed your current plan flawlessly for forty years, what would it actually produce in today's purchasing power — and is that the life you're aiming for, or just the default you inherited? Run the real number, adjusted for inflation and taxes. Most people have never seen it, and it's usually more sobering than the hockey-stick chart implied.
What is your real savings rate — not your 401(k) contribution percentage, but the full share of what you earn that you actually keep and put to work? It's the most controllable variable you have, and for most people it's far lower than they assume.
How many jobs is each of your dollars doing? Most dollars do one — they're either spent, or saved and locked away. What would change if a meaningful portion of your capital could stay compounding and be available to use at the same time?
If you want to pressure-test your own plan against these four variables — including what real losses and inflation do to the projections you've been shown — the Wealth & Liberty library goes deeper on each. Not ready to talk yet? Join the newsletter — one idea a week for thinking more clearly about your own money.
And if you're ready to explore what a capital structure looks like when your dollars are built to improve more than one variable at once, the team at Producers Wealth builds exactly that for business owners and high-income earners.
Wealth & Liberty publishes educational content only. Nothing here is investment, tax, or legal advice, or a recommendation to buy or sell any product. Figures are illustrative projections based on the stated assumptions, not guarantees of future results. Whole life insurance guarantees are subject to the claims-paying ability of the issuing insurer. Consult a qualified professional about your own situation before making financial decisions.

Wealth And Liberty Newsletter
Get exclusive tips and updates


Copyright © 2026 Wealth And Liberty. All rights reserved.
Privacy Notice:
We respect your privacy. Your email address and personal information will never be sold, shared, or misused. Community participation and account registration are optional and exist only to support discussions and content interaction. Please review our Privacy Policy and Disclosures for full details.
Disclaimer :
Wealth & Liberty is an educational platform created to encourage thoughtful discussion around money, freedom, and long-term financial thinking. All information provided is for educational purposes only and should not be considered financial, legal, or investment advice. Any actions you take based on the content are your own responsibility. Always do your own research and consult qualified professionals before making financial decisions.